Free trading journal template for Excel and Google Sheets
A free trading journal template for Excel and Google Sheets, filled with five real Binance trades. Formulas for risk, R, expectancy and drawdown.
This trading journal template is an .xlsx file: one trade per row, and formulas work out the risk, R, net result, expectancy and drawdown. It opens in Excel, Google Sheets, LibreOffice and Numbers, with no macros and no sign-up. Its example rows are five of my real trades on Binance, and below I use them to show how every number is calculated.
What's in the trading journal template
The file has four sheets.
| Sheet | What's on it |
|---|---|
| Trades | 29 columns and 1,000 rows with the formulas in place. Rows 4–8 are examples. |
| Statistics | Your totals, plus tables by mistake, setup, emotion and week. |
| How to use | What to enter in each column and how it is calculated. |
| Lists | Your exchanges, setups, mistakes and emotions for the drop-down lists. |
You fill in the white columns; the grey ones are formulas. This is the part you type: symbol, side, prices, quantity, stop, fees and funding.

The other columns:
- At entry: date and time in UTC, exchange, take profit and the account balance at entry.
- Calculated: risk in $ and in % of balance, gross PnL, net PnL, R, PnL in % of balance, the running total, drawdown and the week.
- Review: setup, mistake, emotion, confidence from 1 to 5, a comment and a link to a screenshot.
Example: five real trades in the template
Rows 4–8 are my trades on Binance USDⓈ-M perpetual futures between 28 August and 5 September 2026. I took every number from the trade's public page in my journal: the average entry and exit prices, the quantity, the fees and the funding. The five were picked to show different cases, not the best result.
| Row | Trade | What it shows |
|---|---|---|
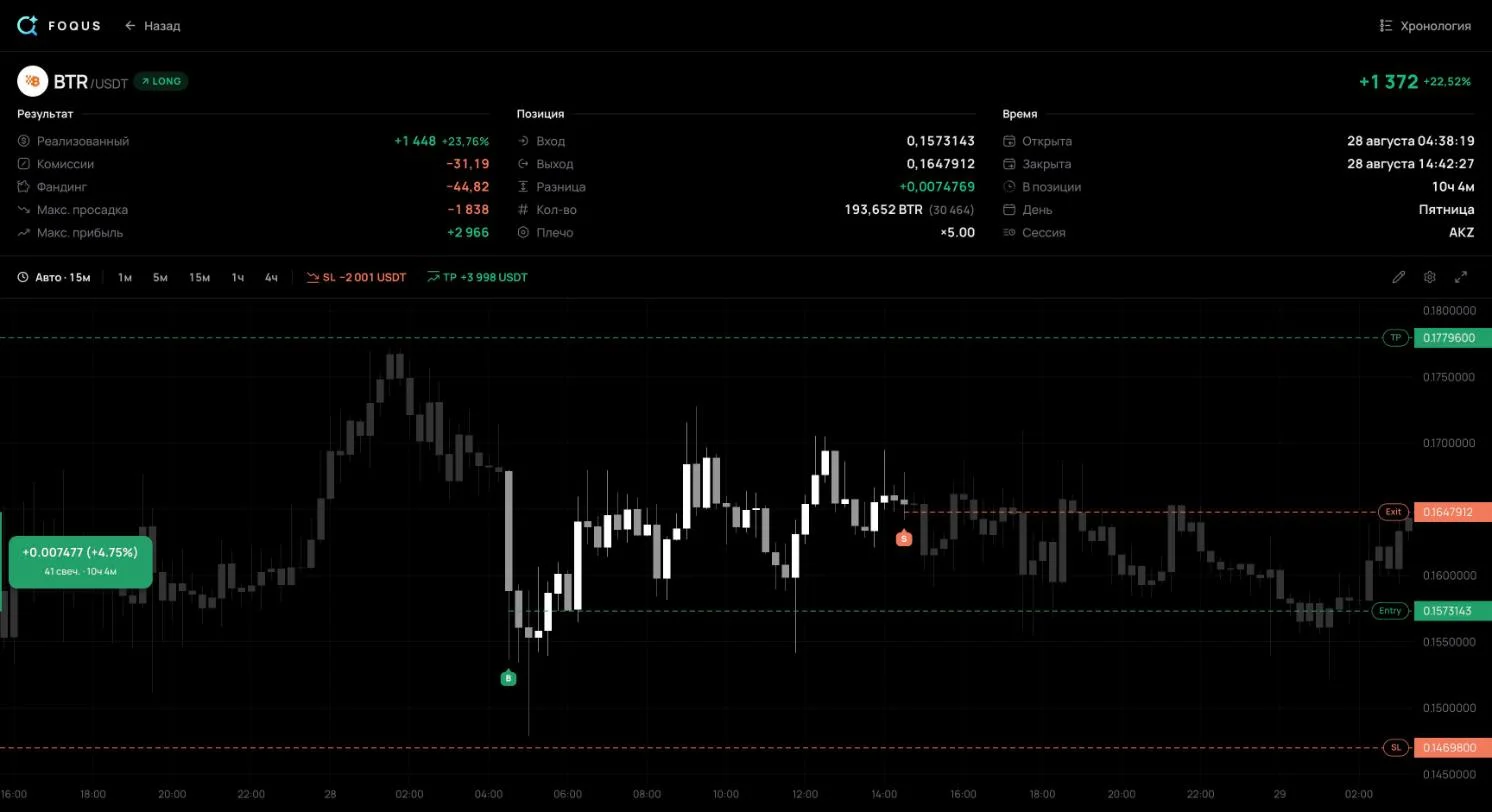
| 4 | #104, BTRUSDT long | An exit between the stop and the target: +0.69R |
| 5 | #136, BTRUSDT long | The stop filled 2.1% worse than its price: −1.81R against a planned −1R |
| 6 | #897, AKEUSDT short | A short's PnL takes the opposite sign: +1.19R |
| 7 | #1138, MARSCOINUSDT long | No stop at the close, so there is no risk and no R |
| 8 | #2011, MARSCOINUSDT long | The stop filled worse than its price: −1.16R |
What a public page doesn't show stays blank in the examples. A visitor's view of the public page shows only the stop at the close. That is the stop in the examples, although the template's own rule asks for the stop at entry. The balance before entry isn't visible, so the “% of balance” columns are empty. Only the trader knows the setup, the emotion and the confidence. The one tag under “Mistake” is “No stop” on #1138, which the page itself shows.
How the template calculates risk, R and the result
The formulas are the same as in any journal. The entry price is the average over all entry fills, the exit price over all exit fills.
Risk, $     = |Entry − Stop| × Quantity × Contract size
Gross PnL   = (Exit − Entry) × Quantity × Contract size
              the sign flipped for SHORT
Net PnL     = Gross PnL − Fees + Funding
R           = Net PnL ÷ Risk
On row 4, trade #104:
- Risk. |0.1573143 − 0.14698| × 193,652 = $2,001.26. That is 1R: what a stop-out would have cost before fees.
- Gross PnL. (0.1647912 − 0.1573143) × 193,652 = +$1,447.92.
- Net PnL. 1,447.92 − 31.19 − 44.82 = +$1,371.91. Funding goes in with its sign: paid is minus.
- R. 1,371.91 ÷ 2,001.26 = +0.69R.
This is the formula side of the sheet. The formula bar shows the R formula of cell S4, as the file stores it.

The template's result can differ from the exchange's by a few cents. For the #897 short the template gives +$2,975.89 and the trade's page in my journal +$2,976.05. The template works from average prices rounded to 7 digits; the journal counts each fill on Binance. Take fees and funding from the exchange's trade history rather than calculating them.
R needs a stop. When the Stop column is empty, as on #1138, risk and R stay blank and the trade counts under “Trades without a stop”. How to choose your risk and size a position from it is covered in the guide to risk per trade; the position size calculator does the sizing for you.
Win rate, expectancy and profit factor
The Statistics sheet totals every closed trade — every trade with an exit price. On the five examples it shows:

Win rate         = Winners ÷ Closed trades           3 ÷ 5 = 60%
Expectancy, $    = Net PnL ÷ Closed trades    3,167.14 ÷ 5 = +633.43
Expectancy, R    = Average R of trades with a stop
                   (0.69 − 1.81 + 1.19 − 1.16) ÷ 4 = −0.27
Profit factor    = All profit ÷ All loss
8,496.76 ÷ 5,329.63 = 1.59In dollars the expectancy is positive; in R it is negative. The biggest profit, +$4,148.97, came from #1138, and it has no stop and no R. Without it, the other four trades lose a quarter of their risk on average. The “By mistake” table says so plainly: the only trade marked “No stop” is the most profitable one. Profit doesn't make a trade without a stop safe: by its MAE, #1138 was down $5,467 on paper at its worst.
Five trades are far too few to judge a strategy. Win rate and expectancy start to mean something over dozens of trades of one setup. What to look at every week and how to review trades is covered in the guide How to Keep a Trading Journal.
How to open the template in Google Sheets
Google's help explains how to import a file.
- Download the file. Use the “Download the template” button at the top of this page.
- Open Google Sheets. Create a blank spreadsheet or open an existing one.
- Choose File → Import. Upload the .xlsx you downloaded.
- Choose “Create new spreadsheet”. That keeps the template apart from the open spreadsheet's data.
- Click Import. The template opens as a new spreadsheet in a new browser tab.
The numbers in the examples were calculated by the same script that builds the file. Excel and Google Sheets recalculate the formulas when they open it.
How to fill in the template
- Fill in the Lists sheet. Add your setups and your usual mistakes: they appear in the drop-down lists and in the statistics.
- Delete the examples. Delete rows 4–8 entirely. If you clear only their contents, you erase those rows' formulas too.
- Log the entry right away. Time in UTC, price, quantity, stop and take profit. The stop is the one you had at entry: risk and R are counted from it.
- Take the exit from the exchange's history. The exit price, fees and funding are in the trade history of the exchange or terminal.
- Review the same day. Setup, mistake, emotion and one sentence: why you entered and what you would do differently.
When a spreadsheet stops being enough
The spreadsheet honestly counts whatever you put in it. The weak spot is the typing. Each trade means typing up to 20 fields, and one forgotten small loss makes the statistics look better than the trading. Scaling in collapses into one average price. Stop moves live only in your memory. MAE and MFE — a trade's largest paper loss and largest paper profit — have to be read off the chart.
An automatic journal takes the trades from the exchange itself. FOQUS keeps such a journal for Binance, Bybit, OKX and MetaTrader 5. It records fees and funding, every move of the stop and the target, and every trade's MAE and MFE. Exchanges connect with a read-only key: FOQUS refuses a key that can trade or withdraw. The journal is free.
Two things to know. FOQUS records trades from the minute you connect, since a venue's old history holds too little to review a trade. For trades from before that, the template stays handy. There is no CSV export of every trade yet — it is still in development. How to create a read-only key is covered in the guide to read-only API keys, and how to connect each platform on the pages for Binance, Bybit, OKX and MetaTrader 5.
Frequently asked questions
Can I open the template in Google Sheets?
Yes: File → Import, upload the file and choose “Create new spreadsheet”. The template has no macros — only ordinary formulas and drop-down lists.
Does it work with Notion?
Notion doesn't run Excel formulas. Download the CSV instead — it holds just the column names. In Notion, choose Settings → Import → CSV to get a database with the same columns. Risk, PnL and R then have to be rebuilt with Notion formulas.
Does the template work for MetaTrader 5 and forex?
Yes. Enter the quantity in lots and, under “Contract size”, the number from the symbol's specification: in MetaTrader 5, right-click in Market Watch → Specification. Put the swap in the funding column.
If the pair's second currency isn't the dollar, as in USDJPY, the formulas give yen, not dollars. Then type two numbers in dollars over the formulas: the profit from the terminal into “Gross PnL” and the risk into “Risk, $”. Risk in dollars = |entry − stop| × lots × contract size ÷ the USDJPY price. For example, 1 lot, entry 150.00, stop 149.50, contract size 100,000: 0.50 × 1 × 100,000 = 50,000 yen, and 50,000 ÷ 150 ≈ $333. Without the risk in dollars, R and “Expectancy, R” are wrong for these rows. The lot size calculator also shows the loss of one lot at the stop in your account currency: multiply it by your lots.
And for crypto futures?
Yes — its examples are Binance futures. For USDT and USDC futures, enter the quantity in coins and leave “Contract size” empty. If the exchange shows the size in contracts, enter how many coins one contract holds. Coin-margined (COIN-M) futures use a different formula. Type two numbers in dollars over the formulas: the result from the exchange's history into “Gross PnL” and the risk at the stop into “Risk, $”. Without the risk in dollars, these trades get a wrong R.
Why is my result a few cents off the exchange's?
The template works from the average entry and exit prices, while the exchange counts each fill. A few cents is the rounding of the average price. If the gap is bigger, check the fees and the funding.
Is the template really free?
Yes: no sign-up and no e-mail. The file is yours — change the columns and the lists to suit you.
Sources
- Google Docs Editors Help: Import data sets & spreadsheets — File → Import, .xlsx support, the “Create new spreadsheet” option.
- MetaTrader 5 Help: Market Watch — the symbol specification and its contract size.
- Notion Help: Import data into Notion — Settings → Import → CSV creates a database from the file's columns.
- My public journal on FOQUS — trades #104, #136, #897, #1138 and #2011: average prices, quantity, the stop at the close, fees and funding. Numbers taken on 8 October 2026.