How to Keep a Trading Journal (With a Real Trade)
What to log before entry, after exit and at review, shown on a real Binance trade: risk and R, MAE and MFE, fees, and what price did after the exit.
To keep a trading journal, log every trade in three passes: the plan before you enter, the numbers right after you exit, and the lessons in a weekly review. The exchange keeps prices, times, fees and funding for you; your setup, your original stop and why you exited exist only if you write them down. Below, all of it is worked through on two real trades from my public journal on Binance, every number taken from their public pages as of 8 October 2026.
Why keep a trading journal?
Your balance shows only the total; a journal shows what it is made of. As of 8 October 2026, 54% of the trades in my public journal are winners, yet the total is −3,041 USDT. Only the per-trade records show why: the average loss is bigger than the average win, and fees took 2,940 USDT. The value is not in the writing itself but in the review: once a week, it shows you what to change. How to run it is covered below.
What to record in a trading journal
| When | What to log | Where it comes from |
|---|---|---|
| Before entry | Symbol, side, time in UTC | you |
| Before entry | Setup: the rule that tells you to enter | only you |
| Before entry | Entry, stop, target, position size | you; the exchange keeps the orders |
| Before entry | Risk to the stop in USDT: that is 1R | calculated: |entry − stop| × quantity |
| After exit | Exit price and time, fees, funding | the exchange's trade history |
| After exit | Result in USDT and in R | calculated: net result ÷ risk |
| After exit | MAE and MFE | the chart while the trade was open |
| After exit | Why you exited, the mistake, your state | only you |
| A day later | Did price reach the target or the stop after you left? | the chart |
R is the trade's risk: what you lose if the stop is hit. The result in R is the net result divided by that risk, so +2R means you made twice what you risked. That is what lets you compare trades of different sizes. The risk per trade guide shows how to choose the risk and size the position from it.
MAE is how far price moved against the position while it was open; MFE is how far it moved in your favor. Both read best in R. The MAE and MFE guide covers them in depth.
Trading journal example: a real trade, logged
On 28 August 2026 I opened a long on BTRUSDT on Binance, a USDT-margined perpetual at 5× leverage. I'll go through it using only what any visitor to the public trade page could see.
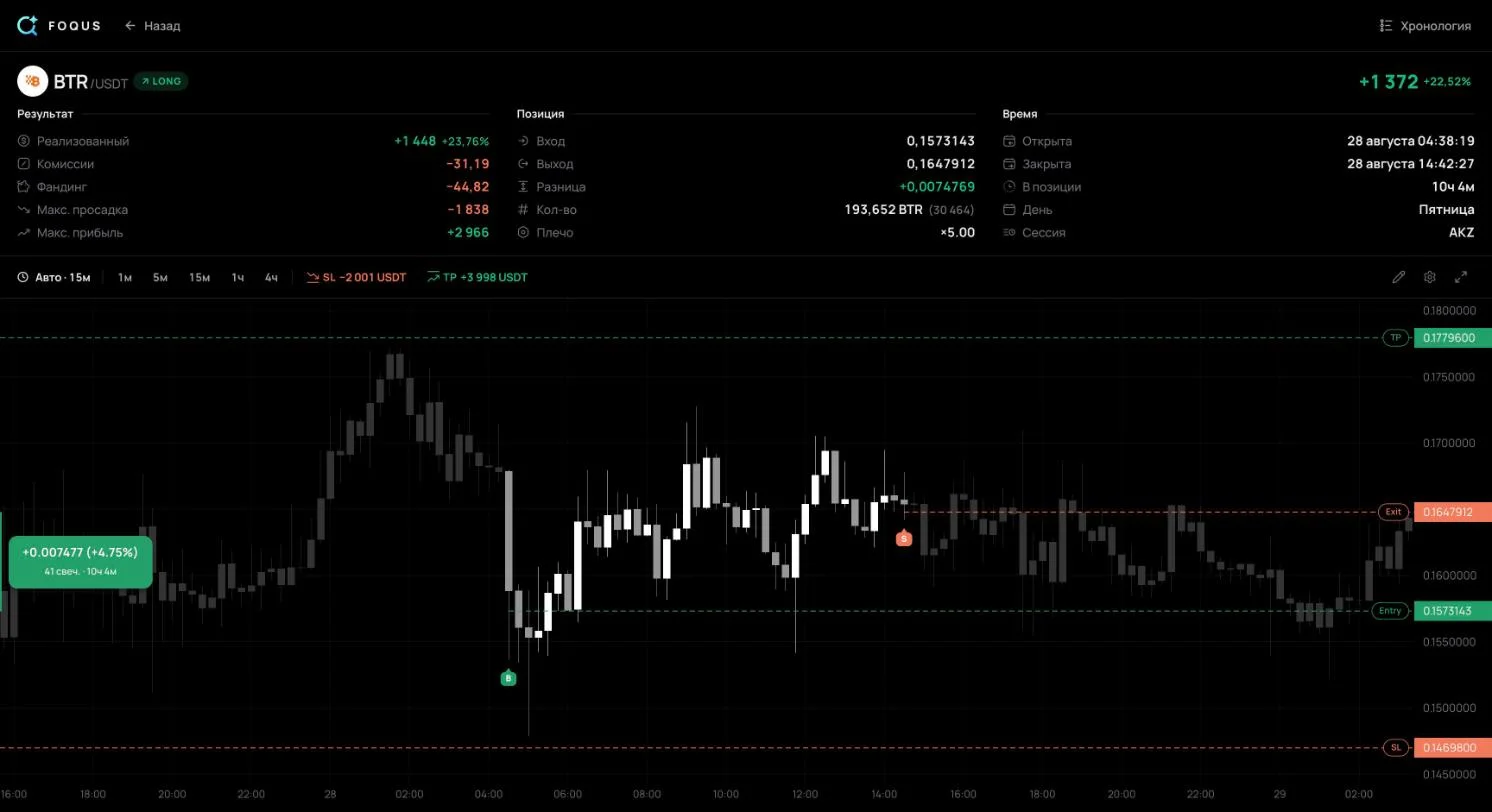
| Field | Entry |
|---|---|
| Time | 28 August 2026, in at 02:38 UTC, out at 12:42 UTC: 10 h 4 min |
| Entry | 0.15731 average price; 193,652 BTR, 30,464 USDT notional |
| Stop and target | 0.14698 and 0.17796 |
| Risk, 1R | 2,001 USDT: the stop was 6.57% away |
| Target | 2R: twice as far as the stop |
| Exit | 0.16479: between the stop and the target, so neither of them |
| Result on price | +1,447.91 USDT, +0.72R |
| Fees and funding | −31.19 and −44.82 USDT |
| Net result | +1,371.91 USDT, +0.69R |
| MAE | −5.98%: 0.14790 at 03:04 UTC, −0.91R |
| MFE | +9.83%: 0.17278 at 07:18 UTC, +1.50R |
| Setup, exit reason, state | not shown on the public page |
The one-line result hides the story. Twenty-six minutes after entry, price had gone 0.91R against the trade, almost to the stop. At 07:18, 4 h 40 min in, the trade was up 1.50R. The exit captured +0.72R on price: 48% of the best move.
I don't give the setup, the exit reason or my state here. They aren't on the public page, and this breakdown sticks to that page alone. Notes and tags on a trade are visible only to the account owner. In your own journal these three fields are yours to fill in: neither the exchange nor a tracking app knows them.
R here is measured from the stop that stood at the close, because the stop's history isn't shown to a visitor who isn't signed in. In your own journal, log the original stop: risk and R are counted from it.

What happened after the exit
Price tagged the 0.17796 target on 29 August at about 09:20 UTC, roughly 20 h 40 min after the exit. Before that it dipped only to 0.15237, still above the 0.14698 stop. Had the position stayed open with the same stop and target, it would have made +3,998 USDT on price, a full 2R, instead of +1,448.
That is hindsight. The figure leaves out another day of funding and the risk of a sharp overnight move, and one trade proves nothing. The value is elsewhere: if you note where price went after every early exit, a few dozen trades will show whether your early exits protect you or cost you money. Without that column you are left with memory, and memory keeps the most painful cases.
The re-entry 74 minutes later
At 13:56 UTC I opened another BTRUSDT long, at 0.16443, almost the price I had just sold at. The stop was tighter: 0.16007, 2.65% away, a risk of 1,001 USDT. The position was bigger: 37,780 USDT notional against 30,464.
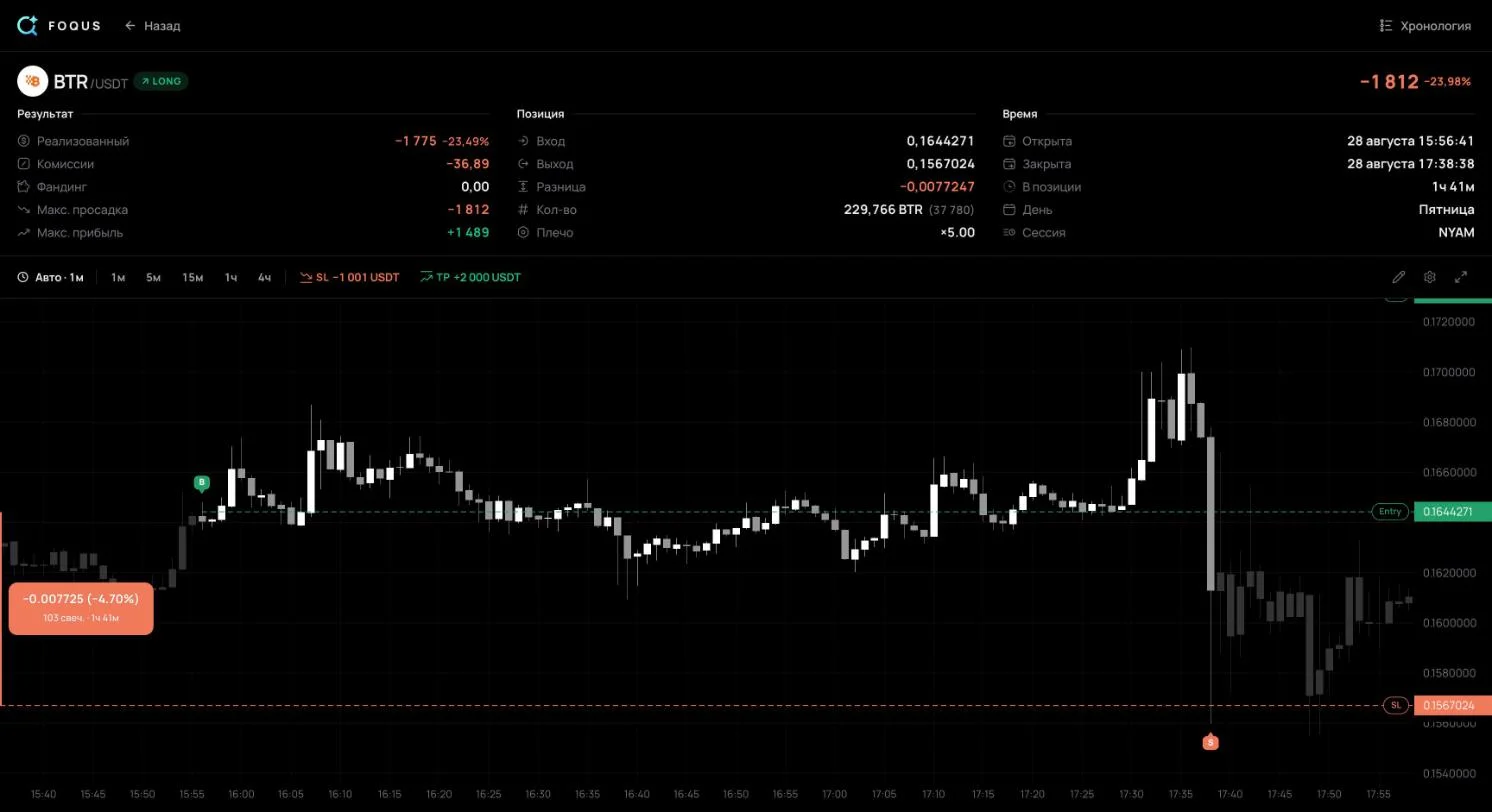
At 15:36 the trade was up 1.51R. At 15:38 a single one-minute candle dropped to 0.15600 and closed at 0.16130, back above the stop. The stop had already fired by then. It filled at 0.15670, 2.1% below the stop price. The result was −1,811.76 USDT, or −1.81R against a planned 1R. Together the two trades lost 439.85 USDT.
A stop-market order becomes a market order once triggered, and a market order fills at the best price available, which in a fast market can be well past the stop. So two things belong in the journal here. First, a "re-entry" mark that links to the previous trade. Second, the gap between the planned risk and the actual loss. If your stop losses regularly come in bigger than 1R, the cause is slippage or a stop that was moved.
How to review your trading journal each week
- Collect every trade of the week. The small and awkward ones too.
- Count four numbers. Number of trades, win rate, average win and average loss, in R or in USDT.
- Work out the expectancy. It is the average result per trade. Positive means the system makes money; negative means it loses.
- Split the trades by setup. A weak setup hides behind a strong one in the total.
- Compare plan and outcome. Look separately at losses bigger than 1R and at early exits, next to what price did after them.
- Pick one change for next week. Write it in the journal so you can check it a week later.
Expectancy = Win rate × Average win − Loss rate × Average lossHere is what that looks like on real numbers: my whole public journal as of 8 October 2026, 65 trades from 16 August to 2 October 2026.
The average winner made +1,435.23 USDT; the average loser, −1,775.80 USDT. Expectancy: 35/65 × 1,435.23 − 30/65 × 1,775.80 = −46.78 USDT per trade. More than half the trades won, yet the account is down, because the average loss is bigger than the average win. Profit factor is total profit divided by total loss; below 1, the account is losing.
There is also a line that shows why fees belong in every entry. On price the trades lost 637 USDT, funding added 537, and fees took 2,940. Without fees the total would be −101 USDT. A journal that skipped fees would show roughly breakeven on an account that is down 3,041.
How many trades before you can trust the numbers?
A win rate is an estimate, not an exact figure. A 95% Wilson interval, the standard way to put a range on a proportion, shows how far it can be off:
| Trades | Win rate | True win rate, 95% |
|---|---|---|
| 20 | 45% | 26% to 66% |
| 65 | 54% | 42% to 65% |
| 100 | 45% | 36% to 55% |
Even after 65 trades the true win rate could be 42% or 65%. That is why the weekly review is for execution mistakes: a moved stop, an entry without a plan, missing fees. A setup is judged on dozens of trades of that setup alone.
Spreadsheet, notebook or app?
- Spreadsheet. Excel or Google Sheets: free and flexible, but you type every number yourself and read MAE and MFE off the chart. The free trading journal template already calculates risk, R and the net result. Try it with the trade above: side LONG, entry 0.1573143, quantity 193,652, stop 0.14698, target 0.17796, exit 0.1647912, fees 31.19, funding −44.82. The template returns a risk of $2,001.26, a net result of +$1,371.91 and +0.69R, the same as the trade page.
- Notebook or Notion. Good for notes and screenshots, weak for numbers: win rate and expectancy have to be worked out separately.
- An app that imports your trades. Prices, times, fees and funding arrive from the exchange through a read-only API key. That is how the trade above was recorded. For MetaTrader 5, the investor password takes the key's place; it is read-only too. The pages for Binance, Bybit, OKX and MetaTrader 5 show how to connect each one. The plan, the exit reason and the lesson are still yours to write.
Trading journal mistakes that hide the truth
- No plan. Without a stop and target set before entry you can't tell what failed, the idea or the execution, and you can't calculate R.
- Logging the stop after you moved it. Risk and R come from the original stop. Log a stop you pushed further away and the loss looks smaller in R than it was against the plan.
- Skipping awkward trades. Impulse entries tend to cost the most. Leave them out and your statistics look better than your trading.
- No fees or funding. In the journal above, that is the difference between −101 and −3,041 USDT.
- Never reading it back. A journal only pays off in the review.
Trading journal FAQ
What should a trading journal include?
Date and time in UTC, symbol, side, entry, stop, target, size and risk in USDT. After the exit: exit price, fees, funding, the result in R and whether you followed your rules. The setup, the exit reason and one lesson are yours to add.
How is a journal different from my exchange's trade history?
The exchange stores your orders and lets you export them. But the history has no plan in it: why you entered, what the original stop was, why you got out. It has no MAE or MFE either; those come from the chart while the trade was open.
Should I record my emotions?
Yes, as one word or a score from 1 to 5. After a month, compare the average result in R for each state. It shows the states in which you trade worse.
Where can I get a free trading journal?
Any spreadsheet with the fields at the top of this guide works. A ready-made one is the free template for Excel and Google Sheets, with formulas for risk, R, expectancy and drawdown.
Where to start
- Before your next entry, write down the stop and the risk in USDT. That is your 1R. Without it you can't express the result, MAE or MFE in R.
- After every early exit, check the chart a day later. Note whether price reached the target or the stop. After a few dozen notes like that, you'll know what your early exits are worth.
Sources
- My public Binance journal, trades 104 and 136: prices, times, fees, funding, MAE, MFE and the totals of 65 trades as of 8 October 2026.
- Binance: How to Download My Order History for USDⓈ-M and COIN-M Futures Orders: the exchange keeps your futures order history and lets you export it.
- Binance: Introduction to Binance Futures Funding Rates: funding is paid between longs and shorts; Binance charges no fee on it.
- Binance: Types of Order on Binance Futures: a stop-market order turns into a market order when triggered, and a market order can slip.
- Van Tharp Institute: A Short Lesson on R and R-Multiples: R as the initial risk set by the stop, results in R multiples, expectancy as the average R multiple.
- NIST/SEMATECH e-Handbook of Statistical Methods: Confidence Intervals: the Wilson method for a confidence interval on a proportion.