MAE and MFE in Trading: Formulas and 3 Real Trades
MAE is a trade's worst open loss, MFE its best open profit. Formulas, R multiples and three real Binance trades: a stop, slippage and profit given back.
MAE (Maximum Adverse Excursion) is the largest open loss a trade showed while it was running. MFE (Maximum Favorable Excursion) is the largest open profit it showed over the same time. A trade's result only tells you where the path ended; MAE and MFE tell you what happened between entry and exit. Below are the formulas and three real trades from my public Binance journal.
What are MAE and MFE?
MAE is the furthest price moved against your position during the trade. MFE is the furthest it moved your way. Both are measured from the entry price, or from the average entry price if you added to the position.
John Sweeney set out the method in his 1997 book Maximum Adverse Excursion. Today the MetaTrader 5 strategy tester, trading platforms and trading journals all calculate both.
Long:   MAE = (Entry − Lowest) ÷ Entry × 100%
        MFE = (Highest − Entry) ÷ Entry × 100%
Short:  MAE = (Highest − Entry) ÷ Entry × 100%
        MFE = (Entry − Lowest) ÷ Entry × 100%

In R:   MAE = |Entry − worst price| ÷ |Entry − Stop|
ETD     = MFE − Result     (given back from the peak)
Capture = Result ÷ MFE     (share of the move you kept)
Take the lowest and highest prices only from the time the position was open. You can express them three ways:
- Percent of entry. Good for comparing trades on one instrument.
- Money. The distance times the position size. It shows what the swing cost you. If you added to the position or took part of it off, use the size that was in the market at that minute.
- R. 1R is the loss your stop would give. An MAE of 0.5R means price went halfway to your stop. How to work out the risk to your stop is covered in the guide to risk per trade.
MAE and MFE example: a real trade
Trade #2011 is my long on MARSCOINUSDT, Binance USDT-M futures. I entered on September 4, 2026 at 21:34 UTC and added to the position at 21:56. The average entry was 0.1916575 and the position 505,214 coins, about 96,828 USDT. At the close the stop stood at 0.18564 and the take-profit at 0.2668. The stop closed the trade on September 5 at 00:36 UTC, 3 h 2 min after entry.
- Risk, 1R. 0.1916575 − 0.18564 = 0.0060175 per coin, or 3.14% of the entry.
- MFE. The high was 0.20666 at 23:16 UTC, about 1 h 42 min after entry: +7.83%, or +2.49R. On paper that was +7,579 USDT.
- MAE. The worst market price while the position was open was 0.18500, in the minute of the exit: −3.47%, or −1.11R. On paper that was −3,363 USDT.
- Exit. The stop was at 0.18564 but filled at an average of 0.184977, 0.36% worse. The price result was −3.49%, or −1.11R.
- ETD. 2.49R − (−1.11R) = 3.6R given back between the peak and the exit.

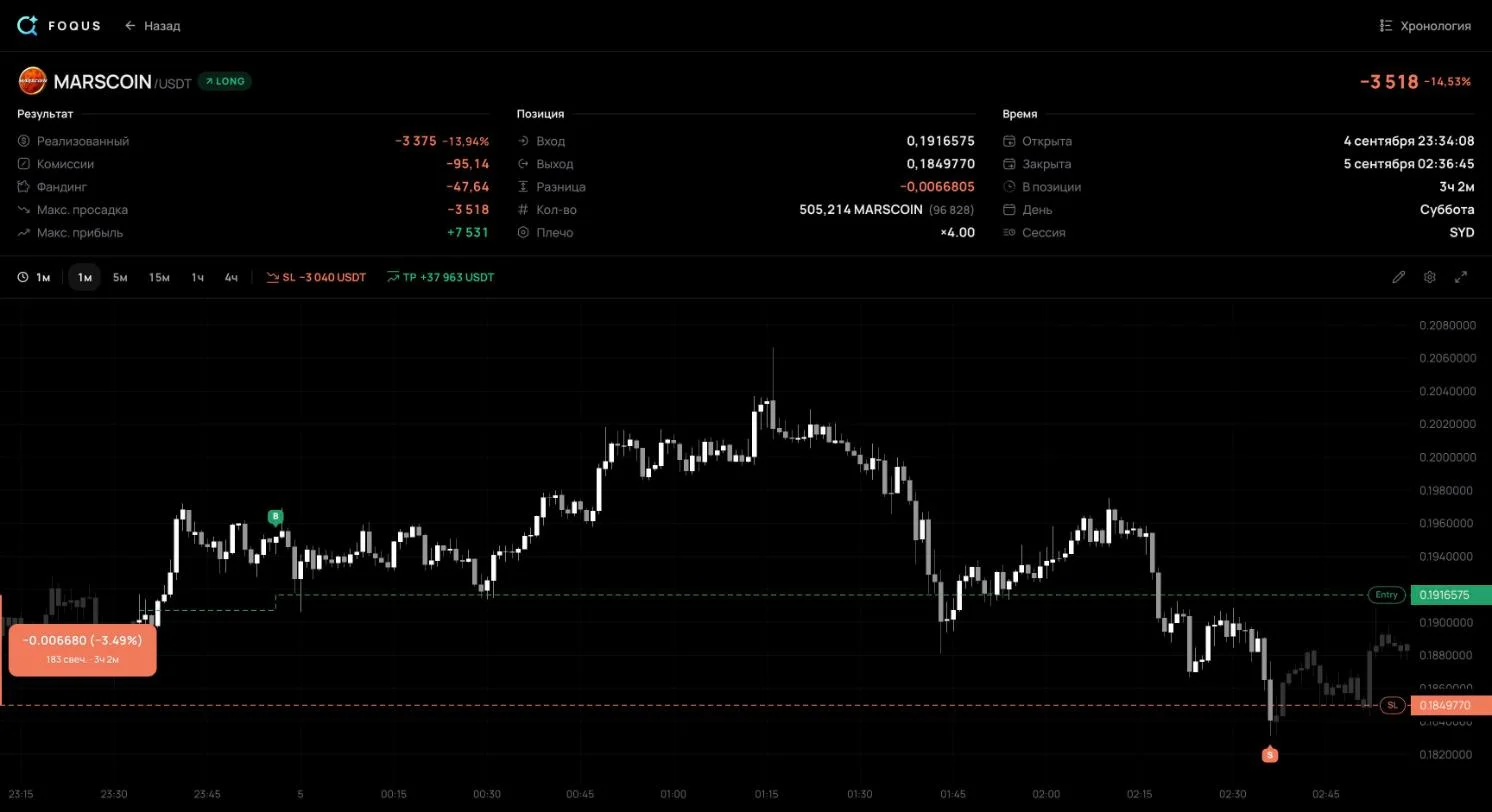
MAE came out beyond 1R: price went past the stop before the position closed, and the stop filled worse than its price. That is slippage. It happens with a stop that becomes a market order once triggered: Binance's help says such an order takes the best price available in the order book, and that price can be worse than expected.
The price result, −3.49%, is even a touch deeper than the MAE, −3.47%. That is not a contradiction. MAE is measured on market prices while the position is open, that is, before the stop fills. The worst such price was 0.18500. The stop itself filled as a market order and went through several levels of the order book. Part of the position closed below 0.18500, and the average fill came out at 0.184977.
One trade proves nothing. But if your journal has many rows like "MFE of 2R or more, result −1R", review how you manage open trades: when to move the stop and when to take part of the position off. In this breakdown I use only what the public trade page shows without signing in. It shows the stop as it stood at the close, but not the history of its moves. That is why R here is measured from the stop at the close.
MAE and MFE after fees and funding
On perpetual futures, MAE and MFE each have two values. One is price only. The other adds the fees and funding charged up to that minute. Funding is a periodic payment between longs and shorts. On Binance it is paid every 8 hours by default, and a position closed before the funding time neither pays nor receives it.
| Trade #2011 | Price only | After fees and funding |
|---|---|---|
| MFE | +7,579.47 USDT | +7,531.06 USDT |
| MAE | −3,363.46 USDT | −3,517.85 USDT |
- At the peak the gap is 48.41 USDT. That is exactly the fees of the two entries, 37.60 and 10.81 USDT. No funding had been charged by then.
- After costs, the worst point is the exit itself. −3,517.85 USDT is the trade's result: −3,375.07 from price, −95.14 in fees and −47.64 in funding.
Work out R and percentages from price, so trades stay comparable. The second number answers a different question: what the swing cost your account. The gap grows with position size and holding time, since fees are charged on the position's value and funding at every payment. On the trade pages these trades come from, the "Max adverse" and "Max favorable" fields showed the second number.
A deep MAE is not always a bad entry
Trade #897 is my short on AKEUSDT. I entered on September 2, 2026 at 23:22 UTC at 0.0161241. At the close the stop stood at 0.017176, 6.52% from the entry. Fourteen minutes in, price reached 0.017131: an MAE of −6.24%, or −0.96R. The stop was 0.04R away and never fired. I closed the position 1 h 12 min after entry, at 0.0148573, for +1.20R and +2,976.05 USDT. MFE was +1.54R, so 0.34R was given back from the peak.
Trade #1138 is my long on MARSCOINUSDT. I entered on September 3, 2026 at 17:22 UTC at 0.1063839. At the close there was no stop, only a take-profit at 0.125. Almost two hours in, at 19:19 UTC, price reached 0.09564: an MAE of −10.10%, −5,467 USDT on paper. Then price turned. I closed the position at 21:25 UTC at 0.1146575, close to the high: +7.78% and +4,148.97 USDT. MFE was +8.33%.

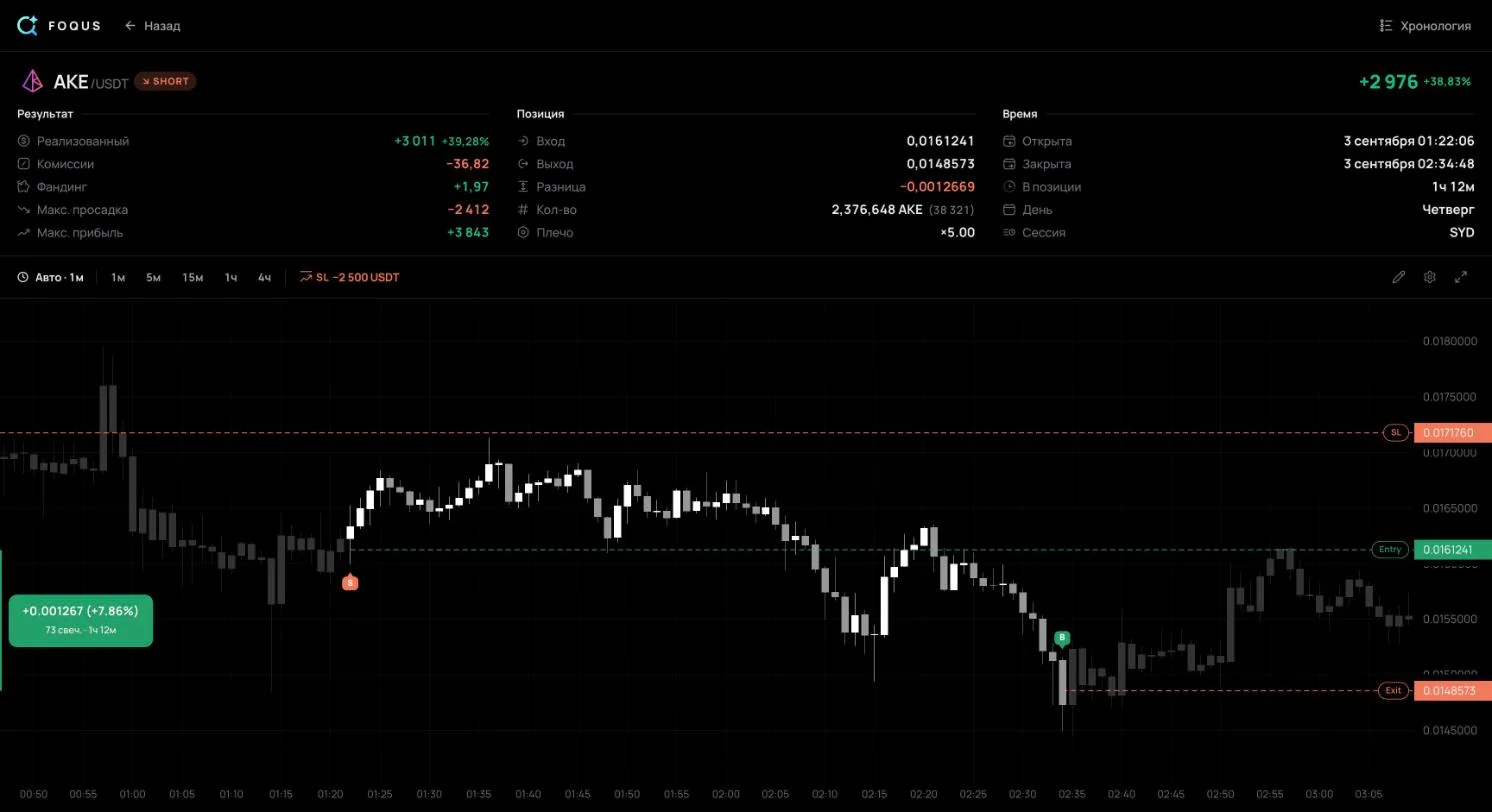
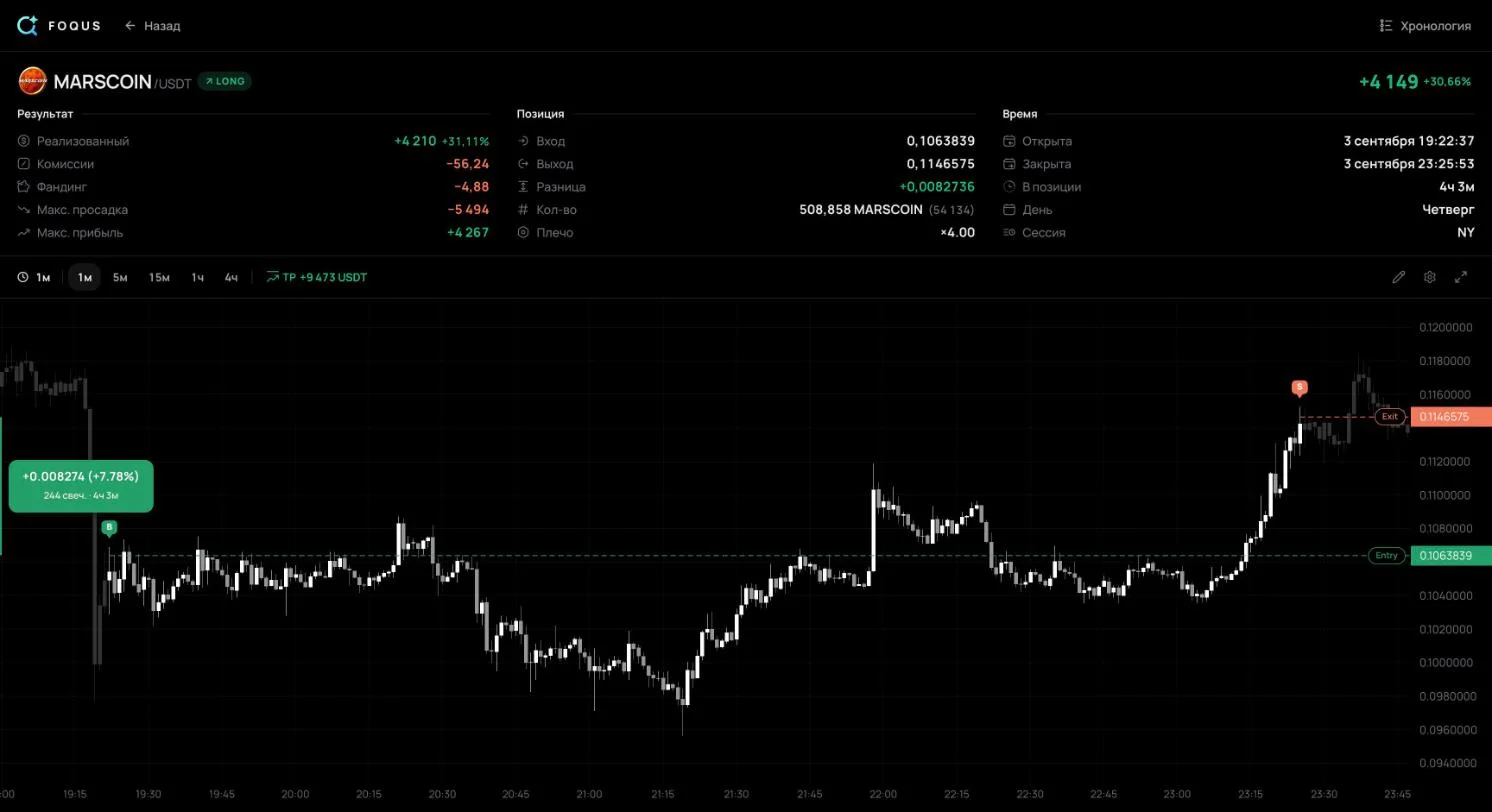
- Depth alone does not condemn an entry. In #897 price went almost all the way to the stop, and the trade still closed 1.2R up. If your winners often show an MAE of 0.8–1R, your stop sits inside normal price noise.
- A profit can hide a risk bigger than itself. In #1138 the open loss on paper, 5,467 USDT, was larger than the final profit, 4,149 USDT. The result hides that; MAE shows it.
- No stop, no R. #1138 had no stop at the close, so its R cannot be calculated and it drops out of any comparison in R.
How to read MAE and MFE across many trades
Plot the trades of one setup on two scatter charts. On the first, MAE runs along the horizontal axis and the result up the vertical. On the second, MFE runs along the horizontal against the same result. Mark winners and losers in different colors. The MetaTrader 5 tester calls these charts "MAE-Profits Distribution" and "MFE-Profits Distribution".
| What you see | What it may mean |
|---|---|
| Winners rarely go against you further than some line, say 0.4R, while losers run to the stop | A trade that goes past that line rarely turns into a winner |
| Many winners have an MAE of 0.8–1R, like #897 | The stop sits inside normal noise and knocks out good trades like these |
| The MFE of winners is 2–3 times their result | You exit early and keep a small part of the move |
| Losers were often 1R or more in profit, like #2011 | Open profit is handed back in full; review how you manage trades |
| Most trades show a small MAE and a large MFE | Entries are precise: price moves your way right after entry |
One way to turn the picture into a rule is the percentile method. The stop goes just beyond the 90th percentile of winners' MAE, a depth only 10% of them went past. The target goes near the median MFE of winners. Silvina Duarte describes the method in a 2026 MQL5 article, and warns that reliable percentiles need a few hundred trades; until then the number only shows a direction.
Test any rule on trades you did not use to find it. A line drawn through old trades can be chance. And split trades by setup: a breakout and a pullback draw different pictures, and in one pile they blur together.
Where to get MAE and MFE for your own trades
- The MetaTrader 5 tester. It calculates MAE and MFE for backtest trades and draws both charts.
- Platform reports. TradeStation draws an MAE scatter chart in its strategy report; NinjaTrader reports MAE, MFE and ETD in its trade statistics.
- A spreadsheet. For each trade, record the worst and best price while it was open and apply the formulas above. The trading journal template already calculates R; add two columns of your own for the low and the high.
- A journal connected to your exchange. It records MAE and MFE for every trade by itself, through a read-only API key. For MetaTrader 5, the investor password takes the key's place; it is read-only too. That is where the numbers in this article come from. Connection guides cover Binance, Bybit, OKX and MetaTrader 5.
What else to record for each trade is covered in how to keep a trading journal.
FAQ
How is MAE different from account drawdown?
MAE is the worst point of a single trade, measured from its entry. Account drawdown is the fall of the whole account from its peak, usually over many trades.
Can MAE be bigger than the stop?
Yes. A stop that fills as a market order can fill worse than its price. In #2011 the stop sat at −1R, while MAE and the result came out at −1.11R. In fast markets the gap can be wider.
What is ETD?
End Trade Drawdown: how much a trade gave back between its peak and the exit, or MFE minus the result. It was 3.6R in #2011 and 0.34R in #897.
How many trades do you need?
The more, the more reliable. Over ten trades the MAE line shifts with every new one. For percentiles, Silvina Duarte puts the need at a few hundred trades. And count them separately for each setup.
What to check in your own journal
- Give-back from the peak. The average ETD of your winners in R: how much of the move you leave to the market.
- Losers with an MFE of 1R or more. How many there are, and why they closed red.
- Winners with an MAE of 0.8R or more. If there are many, your stop is too tight.
- Trades without a stop. Compare their MAE with the final profit.
Sources
- MetaTrader 5 Help: Testing Report: MFE and MAE definitions, the MFE-Profits and MAE-Profits Distribution charts and how to read them.
- John Sweeney, Maximum Adverse Excursion: Analyzing Price Fluctuations for Trading Management (Wiley, 1997): the book that set out the method.
- TradeStation Help: Maximum Adverse Excursion: the MAE scatter chart and its use for stop placement.
- NinjaTrader 8 Help: Statistics Definitions (archived copy): MAE, MFE and ETD, with average ETD = average MFE − average trade.
- Silvina Duarte, Where should your stop-loss really sit? An MAE/MFE excursion analyzer in MQL5 (2026): the stop beyond the 90th percentile of winners' MAE, the target near their median MFE, and a few hundred trades for reliable percentiles.
- Binance: Introduction to Binance Futures Funding Rates: who pays funding to whom, the default payments at 00:00, 08:00 and 16:00 UTC, and closing before the funding time.
- Binance: Types of Order on Binance Futures: a stop-market order fills at the best price in the order book; slippage.
- Trades #2011, #897 and #1138 from my public journal as of October 8, 2026: fills, the stop and take-profit at the close, fees, funding, MAE and MFE.
The trades' numbers were taken from their public pages on October 8, 2026. Percentages, R and both charts were recalculated from that data by a script. Without signing in, a trade page does not show the stop's history, so R is measured from the stop as it stood at the close. Nor does it show funding by individual payment, or my notes on the trades.