Risk Per Trade: How to Calculate Position Size
The position size formula from risk per trade, examples for a USDT perpetual and an MT5 lot, and five of my trades: risk at the stop vs the real result.
Risk per trade is the amount you lose if your stop loss is hit. Position size follows from it: divide the risk in money by the distance from entry to stop. Below are the formula, examples for a USDT perpetual and for a lot in MetaTrader 5, and five of my trades on Binance. In one of them the loss came out 81% bigger than the stop was worth.
What is risk per trade?
Risk per trade is the share of your account you are prepared to lose on one trade. In money, that amount is called 1R, where R stands for risk. The most quoted rules of thumb are the 1% rule and the 2% rule: never lose more than 1% or 2% of the account on a single trade.
Risk is not the size of the position. Risking 1% of a 10,000 USDT account means losing at most 100 USDT if the stop is hit. The position itself can be worth 5,000 USDT or more; how much depends on where the stop is.
Some traders risk a fixed fraction of the current balance, others a fixed dollar amount. With a fixed fraction the risk shrinks after losses and grows after wins: once a 10,000 USDT account drops 10% to 9,000, 1% is 90 USDT. A fixed dollar amount is simpler to track but does not slow you down in a drawdown.
Position size formula
First decide how much of the account you will risk. Then place the stop where the trade idea stops working. The distance from entry to stop is the loss per unit of the asset, for example per bitcoin. Divide one by the other.
Risk ($) = Account balance × Risk per trade (%)
Position size = Risk ($) ÷ |Entry price − Stop price|
The absolute value covers both directions. For a long the stop is below entry; for a short it is above. A short BTCUSDT at 62,500 with a stop at 63,750 has the same 1,250 distance and the same size as the long below.
Order matters. If you pick the size first and then fit the stop to it, every trade carries a random amount of risk.
Example: USDT perpetual futures with leverage
The account is 10,000 USDT and the risk per trade is 1%. You buy BTCUSDT at 62,500 with a stop at 61,250. The stop is 1,250 USDT per bitcoin away: 2% of the entry price.
- Risk: 10,000 × 1% = 100 USDT.
- Position size: 100 ÷ 1,250 = 0.08 BTC.
- Position value: 0.08 × 62,500 = 5,000 USDT.
- Check: at the stop you lose 0.08 × 1,250 = 100 USDT.
On Binance and Bybit the size of a USDT perpetual is set in coins, in steps of 0.001 BTC. On OKX it is set in contracts. One BTC-USDT-SWAP contract is 0.01 BTC, so 0.08 BTC is 8 contracts. A size with a remainder is rounded down to the step, so the risk stays within the plan.
Fees come on top. The base taker fee is 0.05% on Binance and OKX and 0.055% on Bybit. At 0.05% on entry and on exit that is another 4.95 USDT: 2.50 on entry and 2.45 on the exit at the stop. The position size calculator does the same math with your numbers: it shows the loss with fees and the size that keeps fees inside your risk.
Does leverage change your risk?
Leverage decides how much margin the exchange locks for the position. This initial margin is the position value divided by the leverage. Profit and loss are calculated differently: position size × price move. Leverage is not in that formula.
| Leverage | Margin | Loss at the stop |
|---|---|---|
| 5x | 1,000 USDT | 100 USDT |
| 10x | 500 USDT | 100 USDT |
| 20x | 250 USDT | 100 USDT |
High leverage does not make the loss bigger; it frees up money. The temptation to open a bigger position than the calculation allows is where leverage really raises risk.
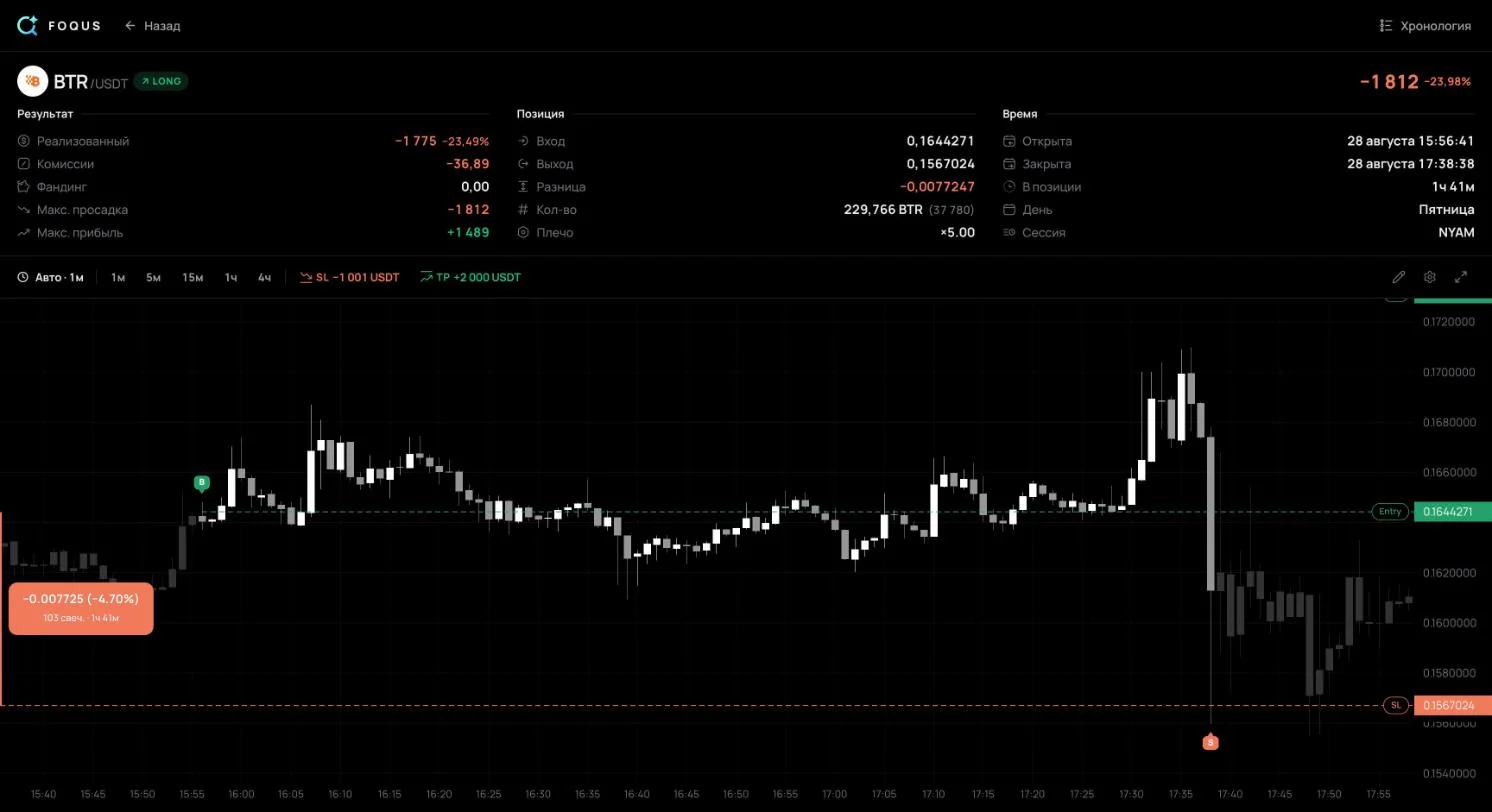
So don't be scared by the percentages on a trade screen. My trade #136 from the section below shows as −23.98% in the journal. That is a percentage of the margin: a 37,780 USDT position at 5x held 7,556 USDT. The account lost 1,812 USDT at any leverage.
In cross margin the whole account balance backs the position. Liquidation is further away, but all the money in the account is at stake.
Forex example: lot size in MetaTrader 5
In forex, size is measured in lots. How many units of currency one lot holds is in the instrument's specification, in the Contract size field. For EURUSD it is usually 100,000 euros. In MetaTrader 5 you open the specification from the Market Watch window: right-click the symbol and choose Specification.
Price moves are counted in pips. For most pairs a pip is the fourth decimal place, 0.0001; for pairs with the Japanese yen it is the second, 0.01. MetaTrader 5 calculates forex profit as (close price − open price) × contract size × lots. So one pip on one lot of EURUSD is worth 100,000 × 0.0001 = $10.
Lots = Risk ($) ÷ (Stop in pips × Pip value per lot)The account is $10,000 and the risk is 1%, so $100. You buy EURUSD at 1.0850 with a stop at 1.0820, 30 pips away. One lot loses 30 × $10 = $300 at the stop. Lots: 100 ÷ 300 = 0.333, rounded down to the volume step: 0.33. The risk after rounding is $99.
Here, too, leverage only changes the margin. MetaTrader 5's help gives forex margin as lots × contract size ÷ leverage: 330 euros at 1:100, 66 euros at 1:500. If the account currency differs from the quote currency, convert the pip value at the current rate. On USDJPY one pip on one lot is worth 1,000 yen; at 150 that is $6.67, and a 40-pip stop gives 0.37 lots. The MT5 lot size calculator does all of this, gold and other account currencies included.
My trades: planned risk against the real loss
The formula promises that at the stop you lose exactly 1R. In practice it comes out differently. Here are five closed trades from my public journal on Binance USDT-M futures, from August 28 to September 5, 2026. 1R here is the loss at the stop that stood when the trade closed. The result includes fees and funding.

They show three things.
The stop is not a cap on the loss. #136 is a long on BTRUSDT. I entered on August 28 at 13:56 UTC at 0.1644271, with 229,766 coins, a 37,780 USDT position. The stop sat near 0.16007, 2.65% below the entry: at the stop I would lose 1,001 USDT. At 15:38 UTC price dropped sharply, and the position closed at an average of 0.1567024, 2.10% below the stop. The loss on price was 1,775 USDT, plus 36.89 in fees. The result: −1,812 USDT, or −1.81R.
On #2011 the gap was smaller. The stop at −3,040 USDT filled 0.36% beyond its price, and fees and funding added 142.78 USDT. The result: −3,518 USDT, or −1.16R. A stop-market order fills at the best price in the book once it triggers, and in a fast move that price can be far from the stop. On coins with a thin book it makes sense to leave a margin: set 1R below what you are prepared to lose.
1R in money varied threefold. It ran from 1,001 to 3,040 USDT across trades opened between August 28 and September 4. If risk were a fixed share of the account, 1R would move only as much as the balance. A threefold spread within a week is a sign the risk was picked trade by trade. The result in R puts such trades on one scale: it shows what each one cost against its own plan.
A trade without a stop has no 1R. #1138 had no stop at the close. Its worst point was −5,494 USDT, 1.81 times the largest 1R of the five. It closed in profit, +4,149 USDT, but it carried more risk than any trade with a stop. How to measure such worst points is in the MAE and MFE guide.
Fees and funding cost these trades between 0.01R and 0.05R. Next to the slippage of #136 that is small change. But they come with every trade, the winners too.
How much should you risk per trade? Losing streaks in numbers
Losses come in streaks, even for a profitable system. Suppose trades are independent and half of them win. Then over 100 trades a streak of 6 or more losses in a row happens with a probability of about 55%, and one of 8 or more about 17%. If 4 trades in 10 win, a streak of 8 or more losses over 100 trades turns up almost every other time: 49%.
How much of the account a streak takes when you always risk the same share of the current balance:
| Risk per trade | 5 losses in a row | 10 losses in a row | 20 losses in a row |
|---|---|---|---|
| 0.5% | −2.5% | −4.9% | −9.5% |
| 1% | −4.9% | −9.6% | −18.2% |
| 2% | −9.6% | −18.3% | −33.2% |
| 5% | −22.6% | −40.1% | −64.2% |
| 10% | −41.0% | −65.1% | −87.8% |
Winning back a loss is harder than losing it. After a 20% drawdown you need a 25% gain; after 50%, a 100% gain. At 1% risk the account halves only after 69 losses in a row; at 10% risk, after seven.
Put your own win rate, stop, target and fees into the risk/reward calculator. It shows the break-even win rate, the expectancy per trade in R and the losing streak to expect over 100 trades.
Frequently asked questions
How much of my account should I risk per trade?
There is no single right number. The most quoted are the 1% and 2% rules. Find your percentage in the table above and answer honestly whether you could sit through 10 losses in a row. This is not investment advice.
What is the 1% rule?
Never lose more than 1% of the account on one trade. It is a rule about risk, not position size: with a 10,000 USDT account and a 2% stop, the position can be worth 5,000 USDT.
Should fees be part of my risk?
Yes, if your risk is meant to be the whole loss at the stop. Then divide the risk by the stop distance plus the entry and exit fees. In the BTCUSDT example the size becomes 0.076 BTC instead of 0.08.
What if my stop fills worse than its price?
Record the real result in R, not the planned one. If it keeps happening, trade smaller on thin coins or leave a margin in the stop. In a trading journal it shows as trades worse than −1R.
Before your next trade
- Size from the stop. Stop and dollar risk first, then position size. Leverage last, and low enough that liquidation sits well beyond the stop.
- Leave room for slippage. Especially on coins with a thin book: my stop at −1R cost −1.81R.
- Record every result in R. It is the only way to see whether your real losses match the plan. The free trading journal template calculates R for you.
Sources
- Bybit: P&L Calculations (USDT Perpetual and Expiry Contracts): P&L of a linear contract is quantity × price move; leverage does not multiply it.
- Binance: How to Calculate Profit and Loss for Futures Contracts: USDⓈ-M sizes are in coins; the P&L formula; initial margin rate = 1 ÷ leverage.
- Binance: Leverage and Margin of USDⓈ-M Futures: maintenance margin and liquidation.
- Binance: Binance Futures Fee Structure & Fee Calculations: 0.05% taker and 0.02% maker for a regular user.
- Bybit: Trading Fee Structure: 0.055% taker on perpetuals at VIP 0.
- OKX: What is OKX perpetual futures: lowest fee tier 0.02% maker, 0.05% taker.
- Binance: Types of Order on Binance Futures: a triggered stop-market order fills at the best available price.
- OKX API: BTC-USDT-SWAP instrument: contract value 0.01 BTC.
- MetaTrader 5 Help: Market Watch: the symbol specification, contract size and volume step.
- MetaTrader 5 Help: Margin Calculation (Retail Forex, Futures): margin = lots × contract size ÷ leverage.
- MQL5 Reference: Symbol Properties: forex profit = (close − open) × contract size × lots.
- IG: Pip definition: a pip is 0.0001, or 0.01 for yen pairs.
- CMC Markets: Lot Size in Forex: standard, mini and micro lots and their pip values.
- Van Tharp Institute: A Short Lesson on R and R-Multiples: R as the initial risk set by the stop.
- My public journal: trades #104, #136, #897, #1138 and #2011 — entry and exit, the stop at the close, fees, funding, the worst point.
The trades' figures were taken from their public pages on October 8, 2026. A public trade page does not show when a stop was set or moved, so 1R is measured from the stop at the close.